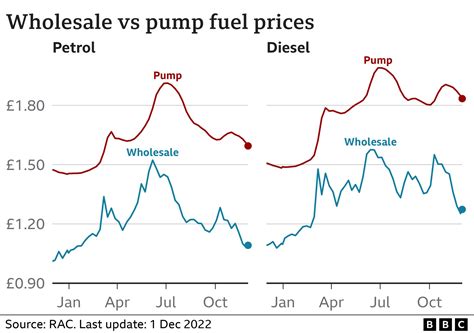
Diesel prices are at all-time highs, and panic has set in. Several Republican senators from Midwest farm states in competitive midterm races have called on the administration to ban diesel exports. Even President Trump expressed support for the proposal. Lawmakers desperately want to curb the pain felt at the pump and throughout the agricultural industry. It’s understandable. But the knee-jerk reaction to “do something” by banning diesel exports is ill advised and would quickly backfire.
Logic might dictate that preventing all diesel from leaving our borders will allow it to fulfill domestic needs first. However, petroleum operates as a global market.
The only way to curtail a diesel surplus would be to cut back on crude oil production altogether—a move that would be economically devastating.
The U.S. fuel network is not designed for nationwide distribution. Nearly 55% of the nation’s refining occurs along the Gulf Coast, producing more than enough diesel for the region. But much of this surplus must be exported because there are very few avenues to ship it to other domestic markets, such as the East and West Coasts, where it is needed. Both those regions rely on imports to satisfy their diesel and gasoline demands.
The U.S. has too few pipelines and cargo capabilities to transport energy to these locations, and storage is not an option; there is only so much space available.
Refineries cannot adjust output quickly. Processing a barrel of crude oil produces fixed proportions of gasoline and other distillates (like diesel and jet fuel); refiners are limited in their ability to shift production levels.
At a time when we are already experiencing significant gasoline shortages and steep prices, constricting supply further would only continue to inflate costs. Voters still rate the economy and affordability as their top concerns; higher conventional gas prices would increase financial strain on household budgets.
U.S. diesel exports represent roughly 20% of global supply, which means they put downward pressure on international prices. Removing that portion would push prices up, and regions dependent on diesel imports—such as the East and West Coasts—would face higher costs.
A ban on diesel and other refined products has been proposed before and soundly rejected. The Biden administration considered the proposal in late 2021 but ultimately decided against it. Several analyses concluded that the action would adversely impact the country.
A 2022 American Council for Capital Formation study predicted that such a ban would shut down roughly 1.3 million barrels a day of refining capacity. More than two-thirds of U.S. consumers would see price increases of about $0.15 per gallon for gas and $0.45 per gallon for diesel, with GDP dropping by $44 billion the following year.
McKinsey & Company similarly found that a ban could initially provide relief for Gulf Coast and Midwest customers but would not last. Import-reliant regions, such as the coasts, would experience diesel price spikes due to global prices rising by at least $0.60 per gallon.
Unfortunately, until there is a durable resolution to ongoing geopolitical conflicts and disruptions abroad that restore a steadier flow of resources, there is no quick remedy for lowering energy costs. Since energy markets and refinery operations are globally interconnected, a rash course of action would have ripple effects across supply chain networks, some touching parts of the country.
Lawmakers should focus on long-lasting solutions at home to provide better insulation from outside forces beyond our control.
A durable fix requires resisting the temptation of quick, politically satisfying moves and instead doubling down on policies that expand supply, modernize infrastructure, and strengthen the resilience of the energy system.
Banning diesel exports would raise prices for most Americans, destabilize global markets, and weaken regions already under strain. Rather than constricting flows in a tightly interconnected network, lawmakers should pursue reforms that unlock investment, improve distribution, and ensure the U.S. can reliably meet its own needs.
The path to lower prices runs through growth and modernization—not restriction.